Bank of Canada Raises Rate to 2.50% — First Hike Since 2023, and Your Mortgage Just Got Pricier
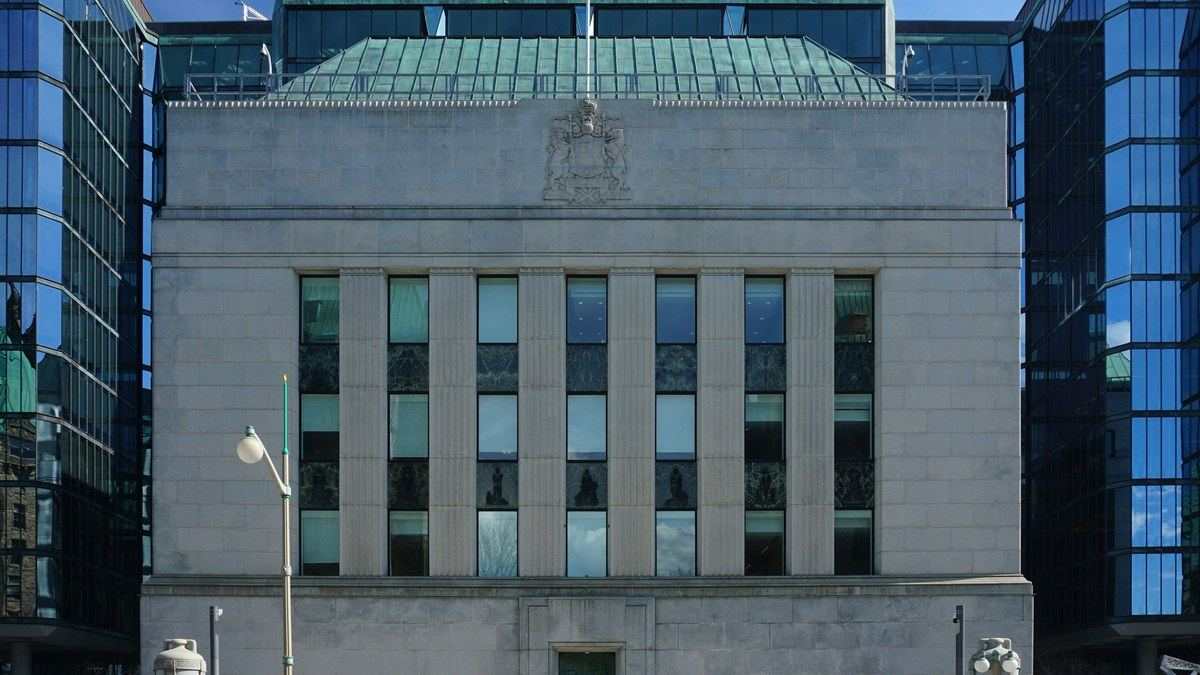
Photo: Wikimedia Commons user 方畢可 / Wikimedia Commons (CC0 1.0) — file photo of the Bank of Canada building in Ottawa, not from the October 28 announcement.
If your mortgage payment felt like it moved overnight, it did — and the reason sits in a granite building on Wellington Street in Ottawa. On Wednesday, the Bank of Canada raised its key rate for the first time in more than three years, and by Thursday morning every big bank had passed the increase on to borrowers.
The central bank lifted its target for the overnight rate by a quarter point, to 2.50 per cent, according to the Bank's October 28 announcement. It is the first increase since July 2023, ending seven straight holds at 2.25 per cent. The Bank Rate is now 2.75 per cent; the deposit rate, 2.45 per cent.
Bank of Canada rate hike October 2026: why Macklem moved now
Governor Tiff Macklem did not dress the decision up. "With the outlook for inflation substantially higher and the economy showing resilience, an increase in the policy rate is needed to reduce the risk that elevated energy prices could spill over and become generalized inflation," he said in his opening statement to reporters in Ottawa, joined by Senior Deputy Governor Carolyn Rogers.
The trigger is the price at the pump. War in the Middle East has kept global oil prices high for longer than the Bank expected. Canadians feel that first at the tank; Macklem's worry is what comes second — trucking firms, factories and shops passing fuel costs on until a gas-price shock becomes higher prices for just about everything.
The numbers behind the call are stark. Statistics Canada put September inflation at 3.1 per cent year over year, driven almost entirely by gasoline — excluding gasoline it was 2.2 per cent. The Bank now expects inflation of about 3.5 per cent by the end of 2026 and 3 per cent on average through 2027, a full point above its July projection, with a return near the 2 per cent target only by mid-2028.
That forecast is why the Bank acted despite a rough jobs picture: September's report showed 68,000 jobs lost and unemployment at 6.5 per cent, according to Statistics Canada, and the Bank calls the housing outlook relatively weak. Economists were split — 19 of 34 in a Reuters poll expected a hike, 15 a hold — but inflation risk won.
Enjoyed this guide?
Canada Pulse is an independent publication. Every guide is researched, written and carefully edited, and kept free forever. If this saved you time or made your life easier, please don't let the effort go unnoticed — support our work with whatever you can, from $1 upward. Every dollar keeps the guides coming.
💛 Donate via PayPalPrime rate 4.70%: what Canada's big banks did today
A Bank of Canada hike only bites when the banks move. All six of Canada's largest banks — RBC, TD, CIBC, BMO, Scotiabank and National Bank — raised prime from 4.45 per cent to 4.70 per cent, effective Thursday, October 29, according to Canadian Mortgage Trends. BMO's own October 28 release confirmed the jump; TD's separate mortgage prime is expected to rise to 4.85 per cent from 4.60 per cent.
What the rate hike means for your mortgage, HELOC and savings
Here is where it lands in your monthly budget. For adjustable-payment variable borrowers, analysts put the cost at roughly $14 a month per $100,000 owed on a 25-year amortization — about $65 a month on a $500,000 balance. On a $400,000 balance with 20 years left, one Ontario brokerage's worked example put the increase at about $51 a month, or $612 over a year.
If your variable payment is fixed, the bill itself does not change — yet. More of each payment now goes to interest and less to principal, stretching the payoff. Fixed-rate holders feel nothing until renewal: fixed rates follow Government of Canada bond yields, not the Bank's announcement. That matters because yields already jumped — Reuters reported the two-year yield touching 3.441 per cent, its highest since August 2024, while the loonie edged up to 1.4035 per US dollar, or 71.25 US cents.
Lines of credit sting a little more, because the whole balance reprices: each quarter point adds roughly $21 a month in interest per $100,000 carried, according to mortgage-industry calculations. Savers get the thin end — posted savings rates at the big banks barely move when the policy rate rises.
Will the Bank of Canada raise rates again in December?
Macklem left the door open. "There could be a need to increase the policy rate further, but given uncertainties, we will proceed carefully," he said. Traders heard him: Reuters reported investors see about a 45 per cent chance of another hike in December, with a second increase fully priced by January. TD Securities strategists added that the Bank "has a tendency to move consecutively after a long pause," with "a lower bar for a subsequent hike in December."
The next scheduled decision lands on December 9, 2026. The Bank's growth forecast gives it some cover — 1.0 per cent growth this year, up from 0.7 per cent in July. My read? This was not a one-and-done warning shot. Macklem raised rates because he thinks energy-driven inflation could take root, and he said so in terms that leave a December move very much alive. If you are renewing soon, run your own numbers now, with your real balance and remaining term, instead of waiting for December's headlines.
Sources
- Reuters — Canadian 2-year yield hits two-year high as BoC hikes interest rates (October 28, 2026)
- Reuters via LA Post — Bank of Canada raises key interest rate, says another hike possible (October 28, 2026)
- Canadian Mortgage Trends — Big banks raise prime rates to 4.70% following BoC hike (October 28, 2026)
- Bank of Canada — Interest rate announcement and release of the Monetary Policy Report (October 28, 2026)
Enjoyed this guide?
Canada Pulse is an independent publication. Every guide is researched, written and carefully edited, and kept free forever. If this saved you time or made your life easier, please don't let the effort go unnoticed — support our work with whatever you can, from $1 upward. Every dollar keeps the guides coming.
💛 Donate via PayPal